

Gross margin commission usually calculates commission from a defined gross-profit amount. The gross-margin percentage describes the economics of the sale; it is not itself the payout basis unless the written terms say so.
The arrangement should specify which sales are eligible, which costs are deducted, the measurement period, when estimated costs become final and how later changes are reviewed.
Those definitions matter more than the label itself. A company may use “gross profit,” “margin” or an internal contribution measure differently, so the commission basis needs to be written down rather than inferred from an accounting term.
This matters because two sales with the same revenue can contribute very different economics when discounts or delivery costs differ. A revenue-based commission will not reflect that difference unless the arrangement includes another margin-related rule.
A margin-sensitive structure can respond differently, but only if Sales and Finance agree on the basis and the participant can understand how the calculation works. For the wider earning, calculation and approval process, see Bentega’s sales commission guide.
What is gross margin commission?
A gross-margin commission arrangement uses a defined profit or margin amount as the basis for calculating commission.
Several terms need to be kept separate.
Eligible net sales revenue is the sales value that qualifies under the arrangement after the specified exclusions. In the examples below, sales are net of discounts and exclude indirect taxes.
Specified cost of sales or service delivery is the cost amount the arrangement says should be deducted from eligible sales. Which costs belong here is a design decision. It should not be assumed from the label alone.
Gross-profit amount is eligible sales minus the specified costs.
Gross-margin percentage expresses that gross profit as a percentage of eligible sales.
Commissionable gross profit may be the same as gross profit, or the arrangement may apply additional eligibility rules before arriving at the amount on which commission is calculated.
Gross profit is also not net profit. Overhead, financing costs, tax and other operating expenses may sit outside the commission calculation, depending on the company’s definition.
The same caution applies to terms such as contribution margin. Gross profit, contribution margin and other internally defined measures can use different cost bases. They should not be treated as interchangeable until the underlying costs have been checked.
Gross margin commission formula
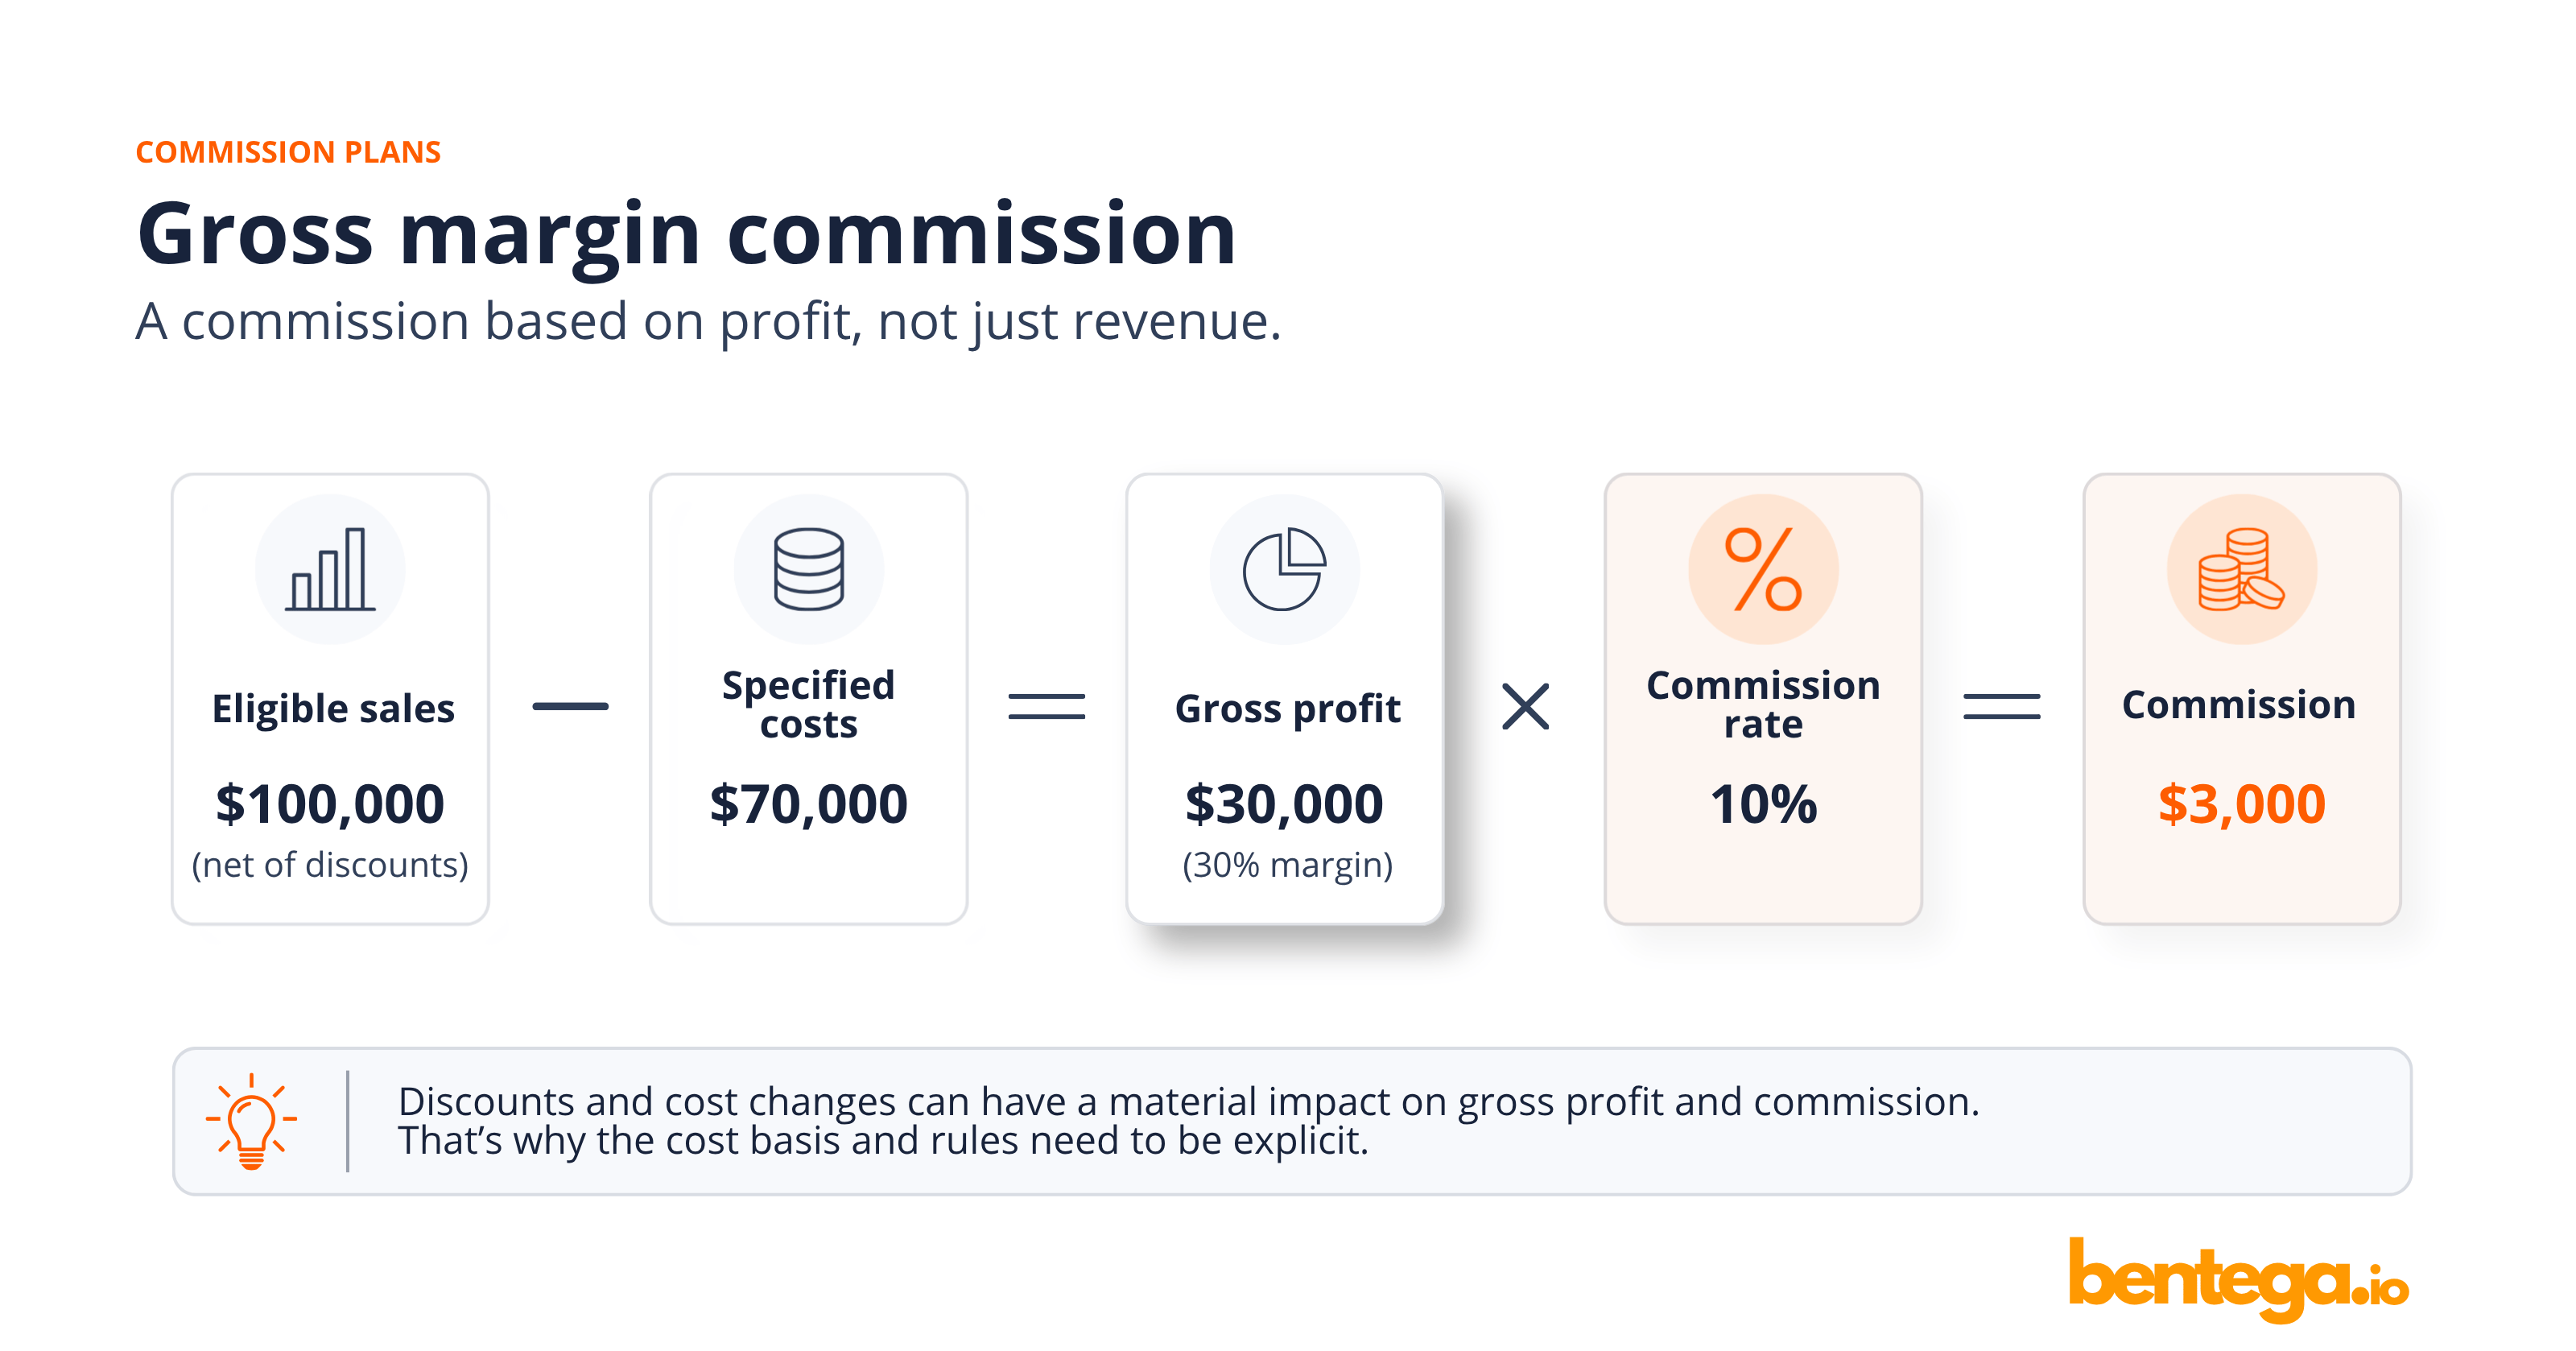
A straightforward gross-profit-based calculation has three steps.
1. Calculate gross profit
Gross profit = eligible sales − specified cost of sales
If eligible sales are $100,000 and the specified costs are $70,000:
$100,000 − $70,000 = $30,000 gross profit
2. Calculate the gross-margin percentage
Gross-margin percentage = gross profit ÷ eligible sales × 100
Using the same numbers:
$30,000 ÷ $100,000 × 100 = 30.00%
The percentage describes the margin. It is not the amount used in the commission calculation in this example.
3. Calculate commission
Commission = defined eligible gross-profit amount × commission rate
At a 10% commission rate:
$30,000 × 10% = $3,000 commission
This illustrative arrangement excludes the commission itself from the gross-profit basis. Otherwise, the formula could become circular.
A company can define another basis in its written terms, but the sequence and included costs need to be explicit.
Worked example: revenue, discount and cost changes
The following three cases use the same monthly measurement period and compare alternative scenarios. They are not cumulative adjustments, and the rows should never be added together.
Assumptions:
- Monthly measurement period.
- Commission rate: 10% of eligible gross profit before commission.
- Sales are net of discounts and exclude indirect taxes.
- The specified cost base excludes commission and any overhead not included in this illustration.
- The revenue-based comparison is a separate alternative paying 3% of eligible sales.
- All amounts are in US dollars.
- Currency amounts are rounded to the nearest dollar and percentages to two decimal places where required.
The original case happens to produce the same $3,000 commission under both alternatives. That does not make the structures equivalent.
With the 10% discount, eligible sales fall by $10,000 while the specified costs remain at $70,000. Gross profit therefore falls from $30,000 to $20,000, and the 10%-of-gross-profit commission falls from $3,000 to $2,000.
Under the separate 3%-of-sales arrangement, the discounted sale would instead produce:
$90,000 × 3% = $2,700
The third row isolates a cost change rather than a price change. Eligible sales remain $100,000, but final specified costs increase from $70,000 to $76,000. Gross profit becomes $24,000 and the gross-profit commission becomes $2,400.
The 3%-of-sales alternative remains $3,000 because the eligible sales amount has not changed.
The comparison shows what each basis is sensitive to. It does not prove which structure will produce better sales results, pricing decisions, retention or return on investment.
How discounts affect commission
A price discount and a reduction in delivery cost are not the same event.
In the discounted example, sales fall from $100,000 to $90,000 while specified costs stay at $70,000. The full $10,000 reduction therefore comes out of gross profit.
That changes the gross-profit commission by:
$10,000 × 10% = $1,000
The revenue-based alternative changes by:
$10,000 × 3% = $300
If delivery costs had fallen at the same time, the gross-profit effect would have been different. That is why how discounts affect sales commission depends on the commission basis and on what happens to the specified costs.
A margin-based basis therefore changes the economics the seller sees when considering a discount. But that does not mean it automatically creates better pricing discipline.
There can also be unintended consequences. A seller may become reluctant to support a strategically useful discount even where the company wants it. Participants may also prefer products and deals whose cost inputs are predictable and easy to verify rather than opportunities with more uncertain implementation or delivery costs.
Those are design questions, not reasons to assume that one structure is universally better.
Which costs should count?
There is no universal cost list for a gross-profit commission arrangement.
The company needs to define the cost basis it intends to use, with Finance validating the definition and source of truth. The definition also needs to be clear enough for Sales and affected employees to understand how it changes their calculation.
Depending on the business, the discussion may include:
- Direct product or service costs.
- Implementation or delivery costs attributable to the transaction.
- Third-party or usage costs associated with delivery.
- Discounts, credits and returns.
- Currency treatment when revenue and costs arise in different currencies.
- Estimated costs versus final actual costs.
The important point is not to copy a generic chart of accounts into the commission rules. It is to decide which costs belong in this specific calculation, identify the source of truth and apply the definition consistently.
Timing matters as well.
For example, a company may know the contract value when a deal closes but only have an estimated implementation cost. If the commission is initially calculated using that estimate, the arrangement should say whether the estimate becomes final for commission purposes or whether it is replaced when actual cost information becomes available.
If a cost definition or another commission rule changes during a measurement period, effective dates should be handled explicitly rather than allowing a current rule to silently rewrite earlier treatment. Bentega’s guide to changing commission rules during a measurement period covers that transition problem in more detail.
What if costs change after approval?
Return to the original example.
The commission was initially calculated using $70,000 of specified costs:
$100,000 − $70,000 = $30,000 gross profit
$30,000 × 10% = $3,000 commission
Now assume final cost information shows $76,000 instead.
The revised calculation is:
$100,000 − $76,000 = $24,000 gross profit
$24,000 × 10% = $2,400 commission
The calculated difference is therefore:
$3,000 − $2,400 = $600
The arithmetic is straightforward. The action is not necessarily straightforward.
Before changing anything, separate four questions:
- What was the original input and result? Preserve the $70,000 cost input and original $3,000 calculation rather than overwriting them.
- What changed, and when? Record the new $76,000 cost information and when it became available or effective for the commission process.
- What do the written rules say? Check whether the arrangement uses estimates, final actual costs or another defined treatment, and how corrections are reviewed.
- Has the amount already been paid? A correction to an unpaid calculation is not the same situation as seeking recovery after compensation has already been delivered.
If the rules support a correction, preserve the original result and record the subsequent correction or adjustment with the responsible owner and approval.
The $600 difference does not by itself create authority to recover $600 from an employee or deduct it from later pay. Post-payment recovery, wage deduction and set-off can raise different questions. See our guide to corrections, adjustments and recovery for those distinctions.
Revenue commission versus gross-profit commission
A useful way to compare commission on profit versus revenue is to hold the commercial result constant and change only the calculation basis.
In the examples above, 3% of $100,000 of eligible sales produces $3,000 regardless of whether specified costs are $70,000 or $76,000.
The gross-profit alternative reacts to that cost change:
- At $70,000 of costs, 10% of $30,000 gross profit produces $3,000.
- At $76,000 of costs, 10% of $24,000 gross profit produces $2,400.
The revenue alternative is simpler because it does not require the same deal-level cost definition. The gross-profit alternative is more sensitive to discounts and specified costs, but that sensitivity also creates additional data, timing and review requirements.
Neither comparison proves what sellers will do in response to the structure.
If you are still deciding between the broader alternatives, use Bentega’s guide to choosing a sales commission structure. For smaller teams, our guide to commission structures for small businesses also discusses when a simpler revenue basis may be easier to operate than an opaque margin calculation.
What to define in a margin-based commission arrangement
The formula only works reliably when the inputs and operating rules are defined.
Before using sales commission on gross profit, document at least these ten points:
- Eligible transactions and revenue. Define which transactions qualify and the event that makes them eligible.
- Discounts, taxes, credits and returns. State whether each item is included or excluded from the sales basis.
- Included and excluded costs. List the cost categories that create the commissionable gross-profit amount.
- Source systems and owners. Identify where eligible sales and cost information come from and who owns each source.
- Estimate-versus-actual rules. State whether estimated costs are final for commission purposes or replaced by later actuals.
- Measurement period and effective dates. Define the period and how rule, role or cost-definition changes are handled across boundaries.
- Rate, thresholds and rounding. Document the commission rate and any other payout mechanics, including the rounding convention.
- Zero or negative profit. State explicitly what happens when gross profit is zero or negative rather than allowing the formula to create an unexplained deduction.
- Approval and correction process. Define who reviews exceptions, approves results and handles later corrections.
- Employee visibility and dispute route. Make it possible for the participant to understand the basis and know where to raise a question.
Bentega’s sales commission guide and template provides a broader structure for documenting eligibility, calculation rules, adjustments, approvals and payout timing.
How Bentega supports margin-based commission workflows
Bentega helps teams run margin-based commission as part of the wider incentive compensation workflow.
Teams can configure the relevant incentive rules, calculate results using defined source data and calculation logic, route results through review and approval, retain calculation and adjustment history, and give relevant users visibility into their results.
The cost definition still needs to come from the company’s agreed rules and data. Bentega applies the logic that has been defined; it does not decide what the company should treat as gross profit.
See incentive compensation workflows in Bentega for the wider product workflow.
Frequently asked questions
Is gross margin commission a percentage of revenue or profit?
In the arrangement described in this article, commission is a percentage of a defined eligible gross-profit amount, not a percentage of revenue and not the gross-margin percentage itself.
For example, $100,000 of eligible sales less $70,000 of specified costs creates $30,000 of gross profit. A 10% commission rate then produces $3,000.
A company’s written arrangement may define another basis, so the actual rules should always be checked.
How does a discount affect gross-profit commission?
If a discount reduces eligible sales while the specified costs remain unchanged, gross profit falls by the amount of the discount.
In the worked example, a $10,000 reduction in eligible sales reduces gross profit from $30,000 to $20,000. At a 10% commission rate, commission falls from $3,000 to $2,000.
If costs also change, calculate those effects separately rather than assuming the discount alone determines the result.
Which costs should be included?
The arrangement should define the cost base. Possible categories include direct product or service costs, implementation or delivery costs and attributable third-party or usage costs.
There is no universal list that every company should use. The company should define the basis, Finance should validate the definition and source of truth, and affected employees should be able to understand how it influences commission.
What happens if estimated costs change after commission approval?
First recalculate the amount using the rules that apply to later cost information. Then establish whether the written arrangement permits the estimate to be replaced, what approval is required and whether the original commission has already been paid.
Preserve the original calculation and record the later correction or adjustment rather than silently replacing the historical result.
A calculated difference does not automatically establish a right to recover compensation that has already been paid.
Is gross-margin commission always better than revenue commission?
No.
Revenue commission is generally simpler to calculate because it does not react to the specified cost changes shown in this article. Gross-profit commission is more sensitive to discounts and costs, but it requires reliable cost definitions, timing rules and review controls.
The appropriate structure depends on the role, economics, available data and outcomes the company intends to reward.
What happens when eligible sales are zero or gross profit is negative?
If eligible sales are zero, the gross-margin percentage is undefined because dividing by zero is not valid.
If eligible sales are positive but specified costs exceed them, gross profit becomes negative. The arrangement should say what that means for commission.
Do not allow a negative formula result to become an automatic deduction from employee pay without an explicit rule and the appropriate review.
Key takeaways
- Gross-margin commission usually applies a commission rate to a defined gross-profit amount, not to the gross-margin percentage.
- The cost basis matters as much as the commission rate. Define which costs count, where the data comes from and whether estimates are later replaced.
- Discounts and cost increases affect a gross-profit-based calculation differently from a revenue-based calculation.
- Preserve the original calculation when later information changes, and treat correction of an unpaid amount separately from recovery after payment.
- A margin-based arrangement is only as understandable as the rules behind the revenue, costs, timing and exceptions.
If you want to see how those rules can be managed as part of a governed incentive workflow, explore Bentega’s incentive compensation platform.