Not every downward change to variable pay is a clawback.
A calculation may be corrected before payment. An unpaid amount may need to be adjusted after review. Or a company may later decide that compensation already paid should be recovered.
Those situations may start with the same underlying event, such as a customer cancellation or incorrect source data, but they represent different stages in the incentive process.
For Finance, HR, RevOps and Payroll, the first step is therefore to establish what happened to the compensation before deciding how the change should be handled.
This article focuses on that operational distinction. It does not determine whether a particular recovery is permitted under a specific employment agreement, compensation policy or local requirement.

What is a clawback in compensation?
In an operational incentive-compensation context, a clawback usually refers to a later adjustment intended to recover variable compensation that has already been paid.
That is different from correcting an amount that has not yet been paid.
Consider three situations:
- A commission is calculated incorrectly and corrected before approval.
- A bonus has been approved but a relevant change is identified before payment.
- A commission has already been paid when the company discovers that the underlying result needs to be reviewed.
All three may involve a lower final amount.
Only the third clearly involves money that has already moved downstream to the employee.
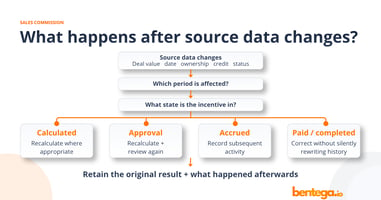
That distinction matters because a good incentive compensation process should preserve the original calculation, the later information and the subsequent decision rather than treating every change as the same event.
Clawback vs calculation correction vs unpaid adjustment
The terminology becomes easier when the compensation state is clear.
The precise terminology can vary between organizations.
What matters operationally is that everyone can see which amount was originally calculated, which state it had reached, what changed and what happened afterwards.
Start with the compensation state
When a number changes, it is tempting to jump straight to the recovery question.
A better sequence is to reconstruct the timeline.
Ask:
- Which compensation plan and rules applied?
- Which performance data created the original result?
- What was originally calculated?
- Had the amount been reviewed?
- Had it been approved?
- Had it moved to an accrued or payable state?
- Had it actually been paid?
- What new data or event caused the review?
- What does the company's plan or policy say about that situation?
- Who should approve the next action?
The same customer event can produce very different operational outcomes depending on when it occurs.
Example: $5,000 was paid, but the corrected result is $4,000
Assume a salesperson was originally calculated to have earned:
Original commission: $5,000
The commission was reviewed and paid.
Later, Finance discovers that one of the source values used in the calculation was incorrect.
Using the corrected source data and the same commission rules, the result becomes:
Corrected calculation: $4,000
The difference is:
$5,000 − $4,000 = $1,000
The calculation tells the company that there is a $1,000 difference between the amount originally paid and the corrected result.
It does not tell the company what the next action must be.
That requires a separate decision based on the applicable compensation arrangement and the company's own review process.
From an operational perspective, the company should preserve:
Original calculation: $5,000
Amount paid: $5,000
Corrected calculation: $4,000
Difference identified: $1,000
Reason for the change: documented
Subsequent decision: documented separately
The important point is that the original $5,000 calculation should not simply disappear from history.
A customer cancellation does not always mean the same thing
Customer cancellations are a common source of confusion in sales commission plans.
Imagine a customer signs a contract and then cancels.
The compensation impact depends on how the plan defines the earning event.
A company might base commission on:
- contract signature
- a defined closed-won event
- customer activation
- invoicing
- customer payment
- completion of a defined initial period
- another explicitly documented event
Those choices lead to different processes.
If the cancellation happens before the earning condition is met
The original commission may still be an estimate.
The relevant question is whether the event required by the plan ever occurred.
If the cancellation happens after calculation but before payment
The amount may need to be reviewed before it moves downstream.
If the cancellation happens after payment
The original earning and payment have already occurred.
Any later adjustment should therefore be treated as a separate event rather than silently rewriting the original calculation.
The same distinction can apply to refunds, credit notes, non-payment, contract amendments and other changes in the underlying commercial data.
Define the earning event before you need it
Many clawback disputes begin much earlier than the clawback itself.
The plan may say that a salesperson earns commission on “sales” without defining what sales actually means.
Is it:
- signed contract value?
- booked ARR?
- invoiced revenue?
- collected revenue?
- gross profit?
- another commercial event?
If that definition is unclear, later events become harder to classify.
For example, suppose a company pays commission when a contract is signed but also wants to reconsider the commission if the customer never pays.
Those are two separate design decisions:
- When is the commission earned?
- What happens if a later event changes the commercial outcome?
Both should be addressed before the situation occurs.
The sales commission guide covers earning events, calculation bases and commission structures in more detail.
Customer churn should not automatically rewrite the original commission
It can also be misleading to treat customer churn as proof that an earlier commission calculation was wrong.
Suppose Sales earns commission when a defined new-business event occurs.
Twelve months later, the customer churns.
The churn may be commercially important, but it does not necessarily mean the original Sales result was calculated incorrectly.
The company may instead decide to:
- leave the original commission unchanged;
- use retention as a diagnostic when reviewing future plan design;
- include an explicit retention condition in future plans;
- create a separate incentive linked to customer quality;
- define a specific later adjustment mechanism.
Those are plan-design choices.
They should not be recreated case by case after the employee has already performed under a different set of rules.
This is also why cross-functional incentive design matters. Sales, Customer Success and Finance may care about different stages of the customer journey without every downstream outcome becoming part of the salesperson's original commission calculation.
Separate a changed calculation from a later decision
A revised result and a recovery decision are not the same thing.
Suppose a deal originally created a $5,000 commission and later source data indicates that the calculation should have been $4,000.
The system can establish the corrected calculation.
The business then has to decide what the $1,000 difference means operationally.
Possible outcomes might include:
- no further action;
- adjustment before payment;
- adjustment in a future incentive period;
- a separate clawback entry;
- further review before any action is taken.
The appropriate choice depends on the company's own compensation terms, policies and circumstances.
Keeping those steps separate prevents a technical recalculation from being mistaken for an automatic business decision.
Why the payment state matters
A variable-pay process usually contains more states than simply “calculated” and “paid.”
For example:
Estimated
The current data and plan rules produce a provisional amount.
In review
The result is being checked or approved.
Approved
The calculation has passed the required decision process.
Accrued, not paid
The amount has received final approval and is awaiting downstream payment.
Paid
Payment has been completed.
Adjusted
A later action has changed the participant's payout position without rewriting the original calculation.
Those states answer an important question whenever something changes:
How far had the original amount moved through the process?
That context often determines whether the company is dealing with an ordinary recalculation, an unpaid adjustment or a later payment adjustment.
For a broader view of these stages, see the incentive compensation management guide.
Do not overwrite the original history
Imagine that Finance reviews the case six months later.
If the system now shows only $4,000, Finance cannot easily tell:
- whether $4,000 was always the result;
- whether $5,000 was originally calculated;
- whether $5,000 was approved;
- whether $5,000 was paid;
- why the calculation changed;
- whether a later adjustment occurred.
A stronger record preserves the sequence.
For example:
That makes the history understandable without changing what actually happened.
What should be documented?
When an incentive amount changes after the original calculation, retain enough information to reconstruct the case later.
That can include:
- applicable plan or component;
- effective dates;
- employee eligibility;
- original performance inputs;
- original calculation;
- review and approval history;
- payment status;
- payment date where relevant;
- changed source data;
- corrected calculation;
- reason for the change;
- decision owner;
- approved adjustment;
- explanation provided to the employee.
The purpose is not documentation for documentation's sake.
It is to make later questions answerable.
If an employee asks why their payment changed, or Finance needs to reconcile the amount, the answer should come from the recorded rules, data and decision history rather than someone's memory.
Handling clawbacks in Bentega
Bentega separates the original incentive calculation from later adjustments.
During an active calculation period, changes in imported source data can update the estimated result.
If an approval-ready calculation is restated, the affected item can return to the beginning of the approval workflow so the revised amount is reviewed again.
Once a bonus has received final approval, Bentega moves it to Accrued, not paid. The approved amount is not silently recalculated if the underlying contract data later changes.
If an adjustment is required after approval, an authorized administrator can record a separate payment adjustment or clawback and document the reason.
The original deal-level calculation remains available.
This means the history can distinguish between:
- the original calculation;
- approval decisions;
- an override where applicable;
- the accrued amount;
- later manual payment items;
- clawbacks;
- the final payable position.
Bentega also keeps later adjustments separate from the original calculation in the payment workflow.
Questions to answer when designing a clawback rule
If a compensation plan includes a clawback or later-adjustment mechanism, define more than the word itself.
Clarify:
- Which event triggers a review?
- Which incentive amounts can be affected?
- At what stage can an amount change?
- What happens before payment?
- What happens after payment?
- How is the revised amount calculated?
- Which source data is used?
- Who reviews the case?
- Who approves the adjustment?
- How is the original calculation preserved?
- How is the change communicated to the employee?
- How are exceptions handled?
- What happens when the participant has changed role or left the company?
- Which questions require HR, Payroll or other specialist review before the company acts?
The answers should match the company's actual incentive process rather than relying on a generic clawback clause copied from another compensation model.
Common mistakes when managing clawbacks and corrections
Calling every downward change a clawback
A calculation correction before payment is not operationally the same as recovering compensation after payment.
Start with the state of the amount.
Changing the original calculation after the fact
If the original result has already been approved or paid, preserve it.
Record the later adjustment separately.
Using customer churn as an automatic trigger
Churn may matter to the business, but its compensation effect should come from the plan design rather than being invented after the event.
Treating a recalculation as the final decision
A new calculation establishes a revised number.
It does not, on its own, determine what the company should do with a previously approved or paid amount.
Leaving ownership unclear
Finance, HR, RevOps, Sales leadership and Payroll may all be involved.
Define who investigates the data, who interprets the plan, who approves the adjustment and who handles downstream processing.
Frequently asked questions
What is a clawback in sales compensation?
In this article, a clawback means a later adjustment intended to recover previously paid incentive compensation.
Companies may use the term differently, so the plan should define what it means in that specific compensation arrangement.
Is a commission correction the same as a clawback?
Not necessarily.
If the amount has not been paid, the business may simply be correcting or adjusting the calculation.
If payment has already taken place, a later adjustment should be recorded separately from the original calculation.
What happens if a customer cancels after commission is calculated?
Start with the plan's earning event and the payment status.
If the commission is still estimated, the result may be recalculated. If it has already been approved or paid, the later event should be reviewed under the company's defined adjustment process.
What happens if a customer cancels after commission is paid?
The cancellation should not automatically erase the original history.
Record what was originally calculated and paid, then handle any later decision as a separate adjustment.
The company's plan or policy should define how such situations are reviewed.
Is customer non-payment automatically a clawback?
No.
Its effect depends on how the incentive plan defines the earning event and any later adjustment rules.
A company that bases commission on collected revenue will have a different process from one that defines earning at contract signature.
Should an approved commission be automatically recalculated when source data changes?
That depends on the company's process and system design.
In Bentega, finally approved amounts are not automatically rewritten when later source data changes. A required post-approval correction is recorded separately as an adjustment or clawback.
Should the original calculation be retained?
Yes from an operational traceability perspective.
Preserving the original result alongside later adjustments makes it possible to explain what happened at each stage of the process.
Can Bentega determine whether a company should recover compensation?
No.
Bentega supports the incentive calculation, workflow, history and later payment adjustments.
The company decides how a particular situation should be treated under its own compensation arrangement and applicable requirements.
Keep the calculation and the later decision separate
The word clawback can make a compensation issue sound simpler than it is.
Sometimes the company is correcting a calculation that has not been paid.
Sometimes an approved amount changes before payment.
Sometimes the employee has already been paid and the company needs to decide how to handle a later difference.
Those situations should not be collapsed into one process.
Start with the original rules and source data. Establish the status the compensation had reached. Record what changed. Then document the later decision separately.
That gives employees, Finance and plan owners a much clearer explanation of what was originally calculated, what changed and what happened afterwards.